Why FCRA Compliant Tenant Screening Is Non-Negotiable for Landlords
FCRA compliant tenant screening means following the rules of the Fair Credit Reporting Act (FCRA) every time you check a tenant’s credit, criminal history, or eviction record — from getting written consent upfront to sending the right notices if you deny an application.
Here is what FCRA compliance requires at a glance:
| Step | What You Must Do |
|---|---|
| Before screening | Get written consent and provide a standalone disclosure |
| Choosing a provider | Use an FCRA-certified consumer reporting agency (CRA) |
| Taking adverse action | Send a pre-adverse action notice with a copy of the report |
| Final decision | Send a final adverse action notice with dispute rights |
| After screening | Securely store and dispose of all consumer reports |
Many landlords run background checks without realizing they are subject to federal law. The FCRA has been on the books since 1970, but violations are still common — and costly. Statutory damages alone can run from $100 to $1,000 per violation, even when the applicant suffered no real financial harm. Over the past decade, FCRA claims have climbed steadily, with settlements easily reaching tens of thousands of dollars.
And the FCRA is just the start. Fair Housing rules, HUD guidelines on criminal records, and a growing web of state and local laws all layer on top. Miss any one of them, and you are exposed.
This guide walks you through every step — what the law requires, where landlords most often slip up, and how to build a screening process that protects you and treats applicants fairly.
I’m Nicole Read, Director of Business Development at Root Management, where I’ve overseen the screening and leasing processes across a rapidly growing portfolio that added 1,450 doors and pushed occupancy from 84.4% to 96.3% in 2025 alone. Building a rigorous, FCRA compliant tenant screening process has been central to that growth, and I’ll share exactly what works in the sections ahead.
Understanding the Fair Credit Reporting Act and Consumer Reports
The Fair Credit Reporting Act is the backbone of consumer protection in the United States. Enacted in 1970, its primary job is to ensure that the information collected by reporting agencies is accurate, private, and used fairly. For us in the property management world, this law dictates exactly how we can handle a “consumer report.”
But what exactly is a consumer report? In the context of leasing, it’s any information provided by a third-party agency that bears on a person’s creditworthiness, character, general reputation, or mode of living. This includes credit history, eviction records, and criminal background checks. Whenever we use this data to make a housing decision, we are stepping into FCRA territory.
One of the most important concepts to master is permissible purpose. Under the FCRA, we can’t just go around pulling people’s credit reports because we’re curious. We must have a valid, legally recognized reason. Evaluating a prospective tenant for a lease is a valid permissible purpose, but we must certify this intent to the screening company before they ever hand over the data.
Defining the Consumer Report in Leasing
In our day-to-day operations in South Bend and Elkhart, we look at several components that make up a consumer report. It’s not just a credit score—though that’s a big part of it. A comprehensive report often includes:
- Credit Scores: Using models like VantageScore, which can score over 30 million more consumers than traditional FICO models.
- Rental History: This includes eviction filings and judgments. Nationally, there are over 36 million FCRA compliant eviction records that help us identify high-risk patterns.
- Criminal Background: Reports might draw from databases covering local courts across all 50 states, totaling over 790 million offenses.
- Character References: If a reporting agency contacts previous landlords or employers to verify “mode of living,” that information becomes part of an “investigative consumer report,” which has even stricter disclosure rules.
Establishing Permissible Purpose for FCRA Compliant Tenant Screening
When we sign up with a screening provider, we are required to certify that we will use the reports only for housing eligibility. This is a legal promise. As part of this process, the screening agency must provide us with a (Notice to Users of Consumer Reports). This document outlines our responsibilities, such as ensuring accuracy and following adverse action procedures. If we use the report for anything else—like checking up on an ex-spouse or a business rival—we are in major legal hot water.
Step-by-Step Guide to FCRA Compliant Tenant Screening
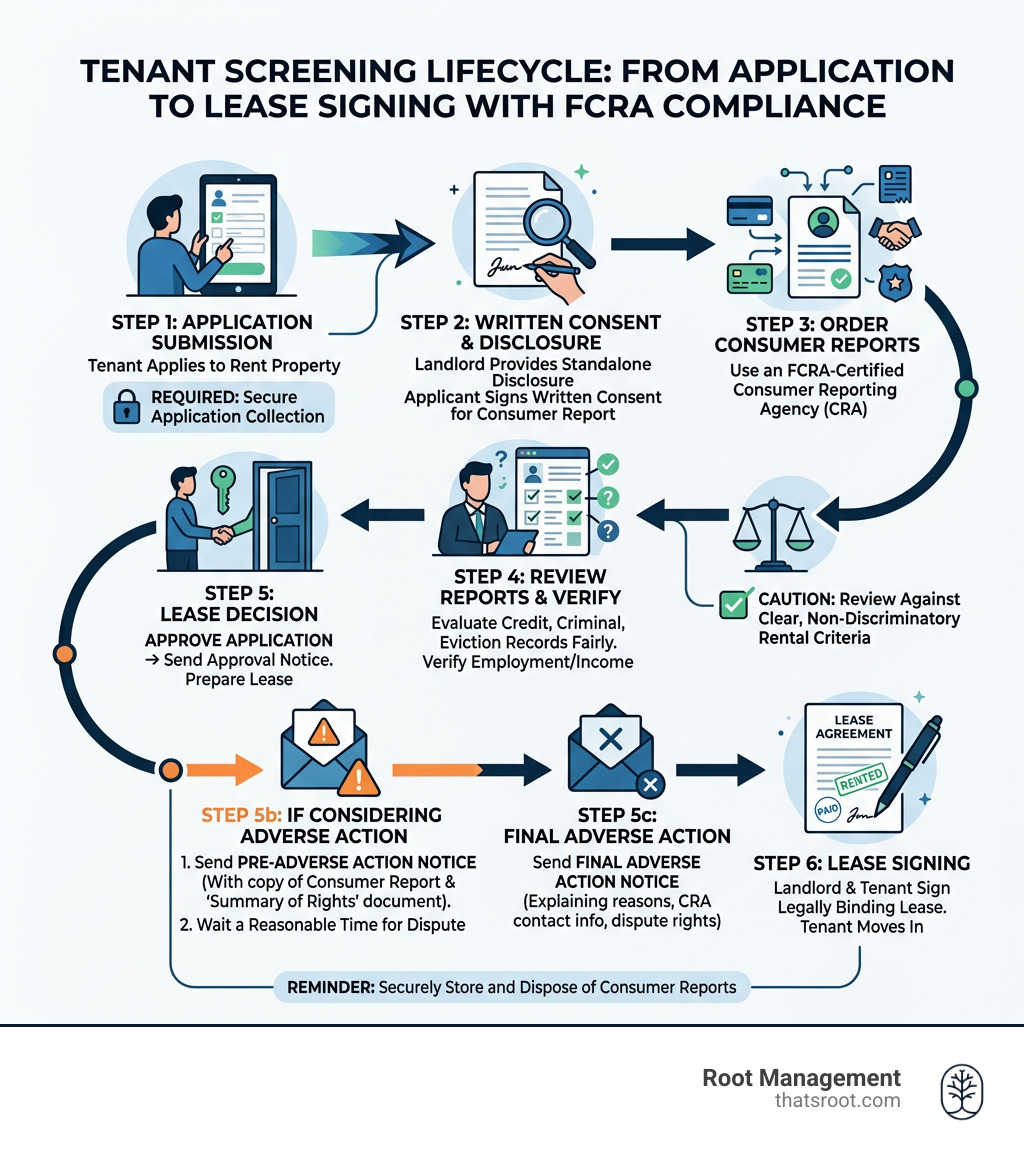
Navigating the screening process without a map is a great way to get lost in a lawsuit. At Root Management, we follow a strict sequence to ensure every applicant is treated according to federal standards. The goal is to be transparent from the very first “hello.”
Mandatory Disclosures and Consent
Before you even think about hitting the “order” button on a background check, you need written consent. But here’s the kicker: the FCRA requires that the disclosure be a separate, standalone document. You cannot simply bury a sentence in the middle of a five-page lease application that says, “We might run your credit.”
To ensure you’re How to Avoid Legal Drama with Your Rental, your disclosure must:
- Be clear and conspicuous.
- Be on its own piece of paper (or its own digital screen).
- Explicitly state that a consumer report will be obtained for housing purposes.
We also make it a point to provide applicants with (A Summary of Your Rights Under the Fair Credit Reporting Act). This document explains that they have the right to know what is in their file and to dispute any inaccuracies. In our experience in the Mishawaka and Granger markets, being upfront about these rights builds trust and keeps us compliant.
Choosing a Provider for FCRA Compliant Tenant Screening
Not all screening services are created equal. Some “instant” background checks you find online might be cheap, but they often rely on outdated or incomplete databases. If you reject a tenant based on a report that has the wrong “John Smith,” you could be liable.
When selecting a reputable consumer reporting agency, look for providers that:
- Verify Data: They should match multiple points of identity (Name, DOB, SSN) to ensure the records belong to the applicant.
- Offer Identity Verification: Some modern platforms use biometric authentication and analyze over 1,000 data points to prevent fraud.
- Provide Compliance Tools: A good provider will help automate the adverse action notice process.
The directory of consumer reporting agencies maintained by the CFPB is a great place to start when vetting vendors.
Navigating Adverse Action: Denials, Deposits, and Disclosures
This is where many independent landlords stumble. Most people think “adverse action” only means denying an application. In reality, an adverse action notice is required for any decision that is less than favorable to the tenant based on their report.
Examples of adverse actions include:
- Denying the application entirely.
- Requiring a higher security deposit than usual.
- Requiring a co-signer.
- Increasing the monthly rent.
The Federal Trade Commission is very clear: if the report influenced your decision even slightly, you must follow the two-step notice process.
The Pre-Adverse Action Process
If you see something in a report that makes you want to deny the applicant, you cannot just send a rejection letter and move on. You must first send a Pre-Adverse Action Notice.
This notice must include:
- A copy of the consumer report you used.
- A copy of the “Summary of Your Rights Under the FCRA.”
The purpose of this step is to give the applicant a “reasonable” window of time to look at the report and tell you if it’s wrong. While the law doesn’t define “reasonable” as a specific number of days, the industry standard is generally five business days. This is their chance to say, “Hey, that eviction on my record was actually dismissed!” For more details, check out the FTC’s guide on Using Consumer Reports: What Landlords Need to Know.
Final Adverse Action Requirements
After the waiting period has passed—and assuming the applicant hasn’t successfully disputed the information—you can send the Final Adverse Action Notice.
According to the FCRA itself, as detailed by the FTC, this final notice must contain:
- The name, address, and phone number of the CRA that provided the report.
- A statement that the CRA did not make the decision to deny the application and cannot explain why it was denied.
- A notice of the applicant’s right to obtain a free copy of their report from that CRA within 60 days.
- A notice of their right to dispute the accuracy or completeness of any information in the report.
| Feature | Pre-Adverse Action Notice | Final Adverse Action Notice |
|---|---|---|
| Timing | Before the final decision is made | After the “reasonable” wait period |
| Contents | Copy of report + Summary of Rights | CRA contact info + Dispute rights |
| Purpose | To allow the applicant to dispute errors | To finalize the decision and inform rights |
Beyond the FCRA: Fair Housing and Criminal Background Guidelines
While the FCRA covers how we get information, the Department of Housing and Urban Development (HUD) and the Fair Housing Act (FHA) cover how we use it. This is particularly true when it comes to criminal records.
The FHA prohibits discrimination based on race, color, religion, sex, national origin, disability, and familial status. HUD has warned that because certain groups are arrested and incarcerated at higher rates, “blanket bans” on anyone with a criminal record can have a discriminatory effect (disparate impact), even if the landlord didn’t intend to discriminate.
HUD Guidelines on Criminal Records
To stay on the right side of fair housing violations, we follow these core principles:
- No Rejections for Arrests: An arrest is not a conviction. HUD states that landlords should not deny applicants based on arrest records alone.
- Differentiate Offenses: A 10-year-old misdemeanor for a minor infraction is very different from a recent violent felony. We must consider the nature, severity, and recency of the crime.
- Individualized Assessment: We should give applicants a chance to provide “mitigating information,” such as evidence of rehabilitation or a long history of good tenancy since the conviction.
- Sex Offender Registry: While we must check the sex offender registry to ensure the safety of our communities, we still need to verify that the data is accurate before taking action.
State and Local Screening Variations
In addition to federal laws, we must be mindful of local screening laws. While Indiana generally follows federal standards, specific programs can add requirements. For example, the Elkhart Rental Inspection Program ensures that properties meet safety standards, which goes hand-in-hand with our goal of placing responsible tenants in quality homes.
We always recommend checking for local ordinances regarding:
- Fee Caps: Some jurisdictions limit how much you can charge for an application fee (often tied to the actual cost of the report).
- Source of Income: In many areas, you cannot discriminate against tenants using Section 8 vouchers or other government assistance.
- Portable Reports: Though not currently mandated in Indiana, some states require landlords to accept “reusable” screening reports to save tenants money.
For more on staying local, see our guide on Elkhart Rental Inspection Program Compliance Made Simple.
Avoiding Compliance Pitfalls and Secure Record Keeping
The “paperwork” doesn’t end once the lease is signed. How you store and destroy that sensitive data is just as important as how you collected it. Inconsistent screening—like checking the credit of one applicant but not another—is one of the fastest ways to trigger a discrimination claim.
As we often say, The Biggest Responsibility of a Property Manager is risk mitigation. That means documenting every step of your process.
Data Retention and Secure Disposal
The FCRA includes a “Disposal Rule” that requires anyone who uses consumer reports to dispose of them securely. You can’t just toss a credit report in the trash where an identity thief could find it.
Best practices for disposal include:
- Shredding: Use a cross-cut shredder for all paper documents.
- Digital Deletion: Permanently delete digital files so they cannot be recovered.
- Encryption: If you store reports digitally, they must be on encrypted, password-protected servers.
How long should you keep these records? While the FCRA doesn’t set a single federal retention period, HUD suggests at least two years. However, many experts—including us at Root Management—recommend a five-year rule. This covers the statute of limitations for most Fair Housing Act claims.
Frequently Asked Questions about FCRA Compliance
How long must I wait after sending a pre-adverse action notice?
While the law uses the term “reasonable,” the industry standard is five business days. This gives the applicant enough time to receive the notice, review the report, and contact the CRA if there is an error. If you move too fast, you risk a lawsuit for denying them their right to dispute.
Can a landlord be sued for FCRA violations even if no financial harm occurred?
Yes. This is the “statutory damages” trap. An applicant can sue you for “willful non-compliance” and win between $100 and $1,000 per violation, plus attorney fees, without ever proving they lost a dime. If you fail to send 50 adverse action notices, that “small” mistake could cost you $50,000 plus your own legal bills.
Does the FCRA apply to criminal and eviction checks or just credit reports?
It applies to all of them. Any report from a third-party agency that contains information about a consumer’s “character, general reputation, personal characteristics, or mode of living” is a consumer report. Whether you are looking at a felony from 1998 or a late payment from last month, the FCRA rules remain the same.
Conclusion
Mastering FCRA compliant tenant screening isn’t just about avoiding fines—it’s about running a professional, ethical, and efficient business. By following these steps, you protect your investment, respect your applicants’ rights, and ensure that your properties in South Bend, Elkhart, and beyond are filled with the best possible residents.
At Root Management, we take this burden off your shoulders. Our personalized, scalable approach means that whether you have a single-family home in Granger or a large multi-family portfolio in Mishawaka, your screening process is always handled with expert precision and full legal compliance.
Ready to fill your vacancies faster while staying 100% compliant? More info about property management services is just a click away. Let us help you turn your rental property into a stress-free, profitable investment.