Why CFPB Tenant Screening Rules Matter for Renters and Landlords
CFPB tenant screening refers to the Consumer Financial Protection Bureau’s oversight of the companies and practices used to screen rental applicants — and the rights you have when a report affects your housing.
Here’s a quick snapshot of what you need to know:
- What it covers: Tenant screening reports include credit history, eviction records, criminal background, and risk scores
- Your key rights: You can get a free copy of your report within 60 days of a denial, and you can dispute errors
- Common problems: Inaccurate records, mismatched identities, and outdated information are widespread
- Who enforces it: The CFPB and FTC enforce the Fair Credit Reporting Act (FCRA), which governs how screening companies handle your data
- 2025 update: The CFPB withdrew several advisory opinions in May 2025, shifting more enforcement responsibility to states
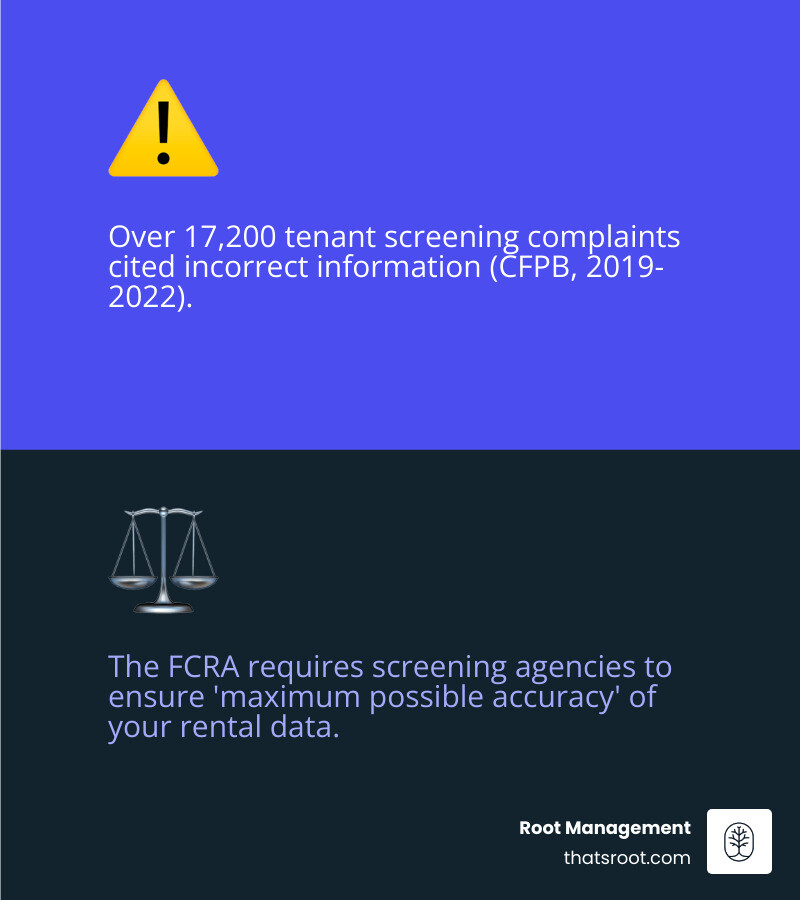
Finding a rental is already hard enough. But imagine being denied an apartment because of an eviction that was dismissed — or because the report mixed up your record with someone else’s. This isn’t a rare edge case. The CFPB received roughly 26,700 complaints about tenant screening between January 2019 and September 2022, and more than 17,200 of those were about flat-out incorrect information.
For property owners, inaccurate screening data isn’t just a tenant problem — it’s a liability. Using a flawed report to reject an otherwise qualified applicant can expose you to legal risk and fair housing complaints.
This guide breaks down exactly how the CFPB regulates tenant screening, what rights renters have, what landlords are responsible for, and what the 2025 regulatory changes mean for everyone involved.
I’m Nicole Read, Director of Business Development at Root Management, where I oversee a rapidly growing residential and commercial portfolio — and navigating fair, compliant CFPB tenant screening practices is central to how we protect both our owners and our tenants. With experience scaling occupancy and managing thousands of leases, I’ve seen how the details of the screening process can make or break a tenancy before it even begins.
Understanding CFPB Tenant Screening Regulations and Your Rights
When we talk about cfpb tenant screening, we are really talking about the intersection of federal law and your daily life. Whether you are looking for a cozy bungalow in South Bend or managing a sprawling apartment complex in Elkhart, the rules of the game are set by the Fair Credit Reporting Act (FCRA).
The FCRA isn’t just a dusty piece of legislation; it’s your primary shield. It mandates that any company providing background checks—known as Consumer Reporting Agencies (CRAs)—must follow “reasonable procedures to assure maximum possible accuracy.” This sounds simple, but as the thousands of complaints show, “reasonable” is often in the eye of the beholder.
One of the most powerful tools you have is the 60-day window. If a landlord in Mishawaka denies your application based on a screening report, they are legally required to tell you. Once they do, you have 60 days to request a free copy of that exact report from the screening company. This allows you to see exactly what the landlord saw, which is the first step in How Tenants Are Having a Better Experience by catching errors before they derail another application.
What Information is Included in Your Report?
A tenant screening report is like a credit report on steroids. While a standard credit report focuses on your financial habits, a tenant screening report pulls from various “specialty” databases. According to the CFPB’s guide on What is a tenant screening report?, these documents typically include:
- Credit History: Your standard FICO score and payment history on loans and credit cards.
- Eviction Records: Filings, judgments, and even dismissed cases (though the CFPB has thoughts on those!).
- Criminal Background: Misdemeanors, felonies, and sometimes even arrests that didn’t lead to convictions.
- Employment Verification: Confirmation of your income and job stability.
- Specialty Lists: Sex offender registries and national terrorist watchlists.
- Risk Scores: Proprietary algorithms that “grade” you as a potential tenant.
In our experience at Root Management, we’ve seen that these reports can vary wildly depending on which vendor a landlord uses. Some are incredibly detailed, while others are essentially a digital shrug.
The Role of Adverse Action Notices
If a landlord takes “adverse action” against you, they must provide a notice. But what exactly is an adverse action? It’s not just an outright denial. It also includes:
- Requiring a co-signer when you wouldn’t otherwise need one.
- Demanding a higher security deposit than other applicants.
- Charging higher rent because of your “risk score.”
If any of these happen, the landlord must provide you with an adverse action notice. This notice must include the name and contact info of the screening company and a statement that the screening company didn’t make the decision—the landlord did. If you’re wondering, What should I do if my rental application is denied?, the answer starts with this notice. It is your ticket to a free report and your roadmap for a dispute.
Common Errors and Why They Happen
Let’s look at the numbers, because they are staggering. Between 2019 and 2022, the CFPB handled over 26,700 complaints specifically about tenant screening. Out of those, a whopping 17,200 were about inaccuracies. That means nearly 65% of the people complaining were dealing with “ghost” evictions or criminal records that didn’t belong to them.
One of the most common issues is the violation of the 7-year rule. Under the FCRA, most negative information (like evictions or civil judgments) should disappear after seven years. However, many screening companies fail to scrub this data, leading to “zombie” records that haunt renters for a decade or more. At Root Management, we believe The Biggest Responsibility of a Property Manager is ensuring that we use data responsibly, which means understanding these limitations.
| Error Type | Common Cause | Impact on Renter |
|---|---|---|
| Name-Only Matching | Software matches records by name only, ignoring DOB or SSN. | Denied for someone else’s crimes. |
| Missing Dispositions | Showing an eviction was filed but not that it was dismissed. | Appears as a completed eviction. |
| Multiple Entries | Listing the same case at different stages (arrest, charge, etc.) as separate events. | Makes a single mistake look like a crime spree. |
| Outdated Info | Reporting negative data older than 7 years. | Prevents “second chance” housing. |
How CFPB Tenant Screening Research Identifies Common Errors
The CFPB has been vocal about “shoddy” practices. One of their biggest targets is name-only matching. This happens when a screening company sees a criminal record for a “James Smith” and attaches it to every James Smith applying for an apartment.
The Bureau’s Advisory Opinion on Name-Only Matching Procedures explicitly states that this practice is often illegal because it doesn’t meet the “maximum possible accuracy” standard. They also find issues with “missing dispositions.” For example, if you were sued for eviction but won the case or paid the rent, the report might still show the filing without the “dismissed” status. This makes you look like a high-risk tenant when, in reality, the legal issue was resolved.
Why Errors Disproportionately Affect Certain Communities
This isn’t just a matter of bad luck; it’s a systemic issue. Research shows that errors in cfpb tenant screening disproportionately hit Black and Hispanic applicants. Why? Much of it comes down to surname diversity. In communities where certain last names are more common, the risk of a “wrong-person” error skyrockets.
Low-income renters also face higher barriers because they are more likely to have faced an eviction filing—even if it was eventually dismissed. Once that filing is in the system, it’s incredibly hard to remove. The CFPB encourages everyone to Review your rental background check regularly to ensure these systemic biases don’t steal your housing opportunities.
How to Audit and Dispute Your Report
You shouldn’t wait until you’re denied an apartment in Granger to see what’s in your file. You are entitled to a free credit report every year from the three major bureaus (Equifax, Experian, and TransUnion) via request your credit report.
However, since tenant screening uses “specialty” reports, you might need to go a step further. We recommend doing an “annual audit” of your own history. If you know you’re going to be moving soon, check the CFPB’s list of tenant screening companies and request your file from the big players like RealPage or TransUnion Rental Property Solutions. If the process feels overwhelming, there is free legal help available for those who qualify.
Navigating CFPB Tenant Screening Disputes and Investigations
If you find an error, don’t just call the company and complain. You need a paper trail.
- Write a formal dispute letter: Clearly identify the error and explain why it’s wrong.
- Include supporting docs: If an eviction was dismissed, include the court order. If a debt was paid, include the receipt.
- The Timeline: Under the FCRA, the screening company generally has 30 days to investigate and respond. They can get a 15-day extension if you provide new info during the window, but they can’t just ignore you.
The CFPB’s Advisory Opinion on Fair Credit Reporting; Facially False Data clarifies that companies can’t ignore “facially false” data—like a report saying you have an eviction from 1950 (unless you’re a very healthy 100-year-old).
Steps to Take After Finding an Error
If the screening company refuses to fix a clear error, you have several options:
- Submit a CFPB Complaint: This often gets a company’s attention faster than a standard dispute.
- File a HUD Complaint: If you believe the error or the denial was discriminatory, file a complaint with the Department of Housing and Urban Development.
- Contact the Data Furnisher: Sometimes the error is at the source (like a former landlord or a local court). Contact them directly to fix the record at the root.
The Impact of Algorithms and Application Fees
Welcome to the age of the “Algorithm.” Many modern landlords don’t even look at your report; they look at a “Rental Risk Score” generated by a computer. These scores are often black boxes—no one quite knows how they are calculated.
This lack of transparency is a major focus of the whole-of-government effort to protect renters. The FTC and CFPB are currently looking into how these scores might be driving discriminatory outcomes. If you want to see what others are saying or add your own voice, you can check the public comments at Regulations.gov.
Understanding Rental Application Fees
In our local markets like South Bend and Mishawaka, application fees are a standard part of the process. On average, these fees run between $40 and $59, but some renters report paying over $100.
The problem? Many of these are “junk fees.” A landlord might pay $20 for a background check but charge the tenant $60, pocketing the difference as “administrative costs.” According to this survey on junk fees, these costs can add up quickly, especially for renters who have to apply to multiple places because of errors on their reports. At Root Management, we strive for transparency in our fees to ensure we are building trust from day one.
The Problem with Automated Risk Scores
The biggest issue with automated scores is that they often rely on unvalidated data. If a screening company’s algorithm sees an “ambiguous” eviction record (which accounts for 22% of 3.6 million records in one study), it might automatically drop your score, even if the case was never completed.
The Bureau has taken action to stop false identification by background screeners who use these automated systems without human oversight. When an algorithm makes a mistake, it doesn’t have a conscience—it just moves on to the next file.
Recent Enforcement and the 2025 Regulatory Shift
The landscape of cfpb tenant screening changed dramatically on May 9, 2025. On that day, the CFPB issued a sweeping notice published in the Federal Register withdrawing dozens of interpretive rules and advisory opinions issued over the previous decade.
Why does this matter? For the last few years, the CFPB had been very active in telling screening companies exactly how to behave. By withdrawing this guidance, the Bureau is essentially saying that the industry should rely more on the “plain language” of the statutes and that state regulators should take a larger role.
The May 2025 Withdrawal of Interpretive Guidance
This withdrawal includes previous guidance on Fair Credit Reporting; Background Screening. For renters, this might mean that federal oversight feels a bit more distant. For landlords and screening companies, it means they must be even more diligent about following the core FCRA laws, as they can no longer rely on the “interpretive” safety net provided by the Bureau.
Some experts worry this could lead to a return to “sloppy” practices like name-only matching, while others believe it will reduce “regulatory overreach.” Regardless of the perspective, the statutory obligation to provide accurate reports remains in full effect.
How State Regulations Fill the Gap
With the federal government stepping back slightly, state laws are becoming more important. For example, in Indiana, we follow specific state rules regarding how long certain records can be kept and what can be asked during the application process.
If you are a multi-state renter, you need to know that your rights in South Bend might be different than your rights across the border in Michigan. The CFPB’s guidance on Fair Credit Reporting; File Disclosure still provides a baseline, but state-level protections are where the real “filling of the gap” is happening.
Frequently Asked Questions about CFPB Tenant Screening
Can expunged or sealed records be included in my report?
No. If a record has been legally expunged or sealed, it is restricted from public access. The CFPB has made it clear that including these records in a background check is a violation of the FCRA because they are no longer part of the public record and their inclusion undermines “second chance” opportunities.
How long can an eviction stay on my tenant screening report?
Under federal law, negative information like evictions or civil judgments can generally stay on your report for seven years. After that, it must be removed. If you see an eviction from eight years ago on your report, that is a clear error you should dispute immediately.
What should I do if my report has someone else’s criminal record?
This is usually a result of “name-only matching.” You should immediately file a written dispute with the screening company, providing your Social Security number and date of birth to prove you are not the person in the record. If they refuse to fix it, you can submit a complaint to the CFPB.
Conclusion
Navigating cfpb tenant screening doesn’t have to be a horror story. Whether you’re a renter looking for your next home in Granger or a property owner wanting to ensure your screening process is beyond reproach, knowledge is your best asset.
At Root Management, we take these regulations seriously. We provide full-service property management that balances the need for thorough screening with the legal and ethical requirements of fair housing. From South Bend to Elkhart, our personalized and scalable approach ensures that every tenant is treated fairly and every owner is protected.
Ready to experience a better way to manage or rent? More info about our services is just a click away. Let’s make your next rental story a success.