What Commercial Tenant Screening Services Actually Do (And Why You Need Them)
Commercial tenant screening services are professional tools that help property owners evaluate the financial health, legal standing, and creditworthiness of a business before signing a lease. Here’s what they typically cover:
- Business credit reports – payment history, credit limits, and debt trends
- Legal filings – bankruptcies, judgments, tax liens, and lawsuits
- UCC filings – liens on business assets held by lenders
- Criminal background checks – on the business principals or lease signers
- Identity and employment verification – for the individual signing the lease
Most reports are available the same business day, with pricing typically ranging from $80 to $85+ depending on the depth of the report.
Signing a lease with the wrong commercial tenant is expensive. Empty spaces, legal disputes, and unpaid rent can quietly erode your returns for months — sometimes years.
Unlike residential screening, commercial screening requires digging into two layers: the business entity itself and the person signing the lease. A business can look healthy on the surface while the owner carries serious personal debt, or vice versa. Standard residential screening tools simply aren’t built to catch that.
Providers like APScreen — which serves over 90% of commercial asset and property management companies in the U.S. — have built entire services around this specific challenge. That’s not a small market. It tells you how common this problem really is.
I’m Nicole Read, Director of Business Development at Root Management, where expanding into commercial properties has made commercial tenant screening services a critical part of how we protect owner investments and maintain high occupancy. Below, I’ll walk you through everything you need to know to screen commercial tenants confidently.
Why Commercial Tenant Screening Services are Essential for Property Owners

When we talk about Commercial Property Management in markets like South Bend or Elkhart, we aren’t just talking about collecting checks. We are talking about risk management. Commercial leases are often long-term commitments—five, ten, or even fifteen years. If a tenant fails in year two, the cost to find a replacement, pay new leasing commissions, and potentially fund new tenant improvements can wipe out years of profit.
Using professional commercial tenant screening services is essential for several reasons:
- Asset Protection: A business that is struggling financially is less likely to keep up with property maintenance. Screening helps ensure the tenant has the liquidity to respect your physical asset.
- Revenue Stability: You need to know if a company has a history of “Days Beyond Terms” (DBT). If they consistently pay their vendors 30 days late, they’ll likely do the same to you.
- Eviction Prevention: The average cost of an eviction can exceed $3,500 in legal fees and lost time. In the commercial world, where rent amounts are significantly higher, that number can skyrocket.
- Professional Liability: As a landlord, you have a responsibility to other tenants in the building. Screening for criminal backgrounds or Global Homeland Security issues ensures you aren’t bringing a “bad actor” into a shared professional environment.
Before you start, it is vital to understand the Legal info on commercial screening requirements. While commercial screening isn’t always subject to the exact same “Fair Housing” rules as residential, you must still comply with the Fair Credit Reporting Act (FCRA) when looking into individual lease signers.
Key Differences Between Commercial and Residential Screening
One of the biggest mistakes we see new commercial landlords make is trying to use a residential screening app for a business lease. It’s like trying to use a lawnmower to clear a cornfield—it’s just not the right tool for the job.
Entity vs. Individual
In residential screening, you are looking at a human being’s FICO score and their history of paying a cell phone bill. In commercial screening, the primary “applicant” is often an LLC, a Corporation, or a Partnership. This entity has its own credit profile, separate from the owners.
Personal Guarantees
Because many small businesses (especially those under 6 months old) have “thin” credit files, we often require a personal guarantee. This means we screen the business and the individual owner. If the business folds, the individual is still on the hook.
Data Points Comparison
To make this clearer, let’s look at how the data differs:
| Feature | Residential Screening | Commercial Screening |
|---|---|---|
| Primary Subject | Individual Person | Business Entity + Principal |
| Credit Score | FICO / ResidentScore | Paydex / Intelliscore / Business Profile |
| Public Records | Evictions, Criminal | UCC Filings, Tax Liens, Judgments |
| Financial Focus | Personal Income / Debt | Cash Flow, Trade Lines, Vendor History |
| Verification | Employer / Past Landlord | Bank Relationships, Business Longevity |
Operational Stability
Residential tenants just need a job. Commercial tenants need a viable business model. We look at industry-specific risks. For example, retail tenants are generally considered less stable than medical or office tenants unless they are a well-established franchise. If a business is moving from a large space to a smaller one, that’s a red flag for downsizing. If they are expanding, it’s a sign of growth—but can they handle the increased overhead?
Anatomy of a Comprehensive Commercial Tenant Screening Report
When you order a report through commercial tenant screening services, you aren’t just getting a “thumbs up” or “thumbs down.” You’re getting a deep dive into the company’s DNA. At Root Management, we look for specific components to build a full picture.
Credit Bureaus and Scoring Models
Most commercial reports pull from Experian Business or Equifax Commercial. You might see a “Commercial Intelliscore,” which ranks risk from 1 (low) to 5 (high). This score predicts the likelihood of a business becoming seriously delinquent in the next 12 months.
UCC Filings
This is a big one. A Uniform Commercial Code (UCC) filing tells you if a lender has a lien on the business’s assets. If a tenant has five different UCC filings, it means they’ve borrowed heavily against their equipment or inventory. If they go bust, you might be fighting other creditors just to get your hands on the equipment left in the space.
Days Beyond Terms (DBT)
This metric shows how many days past the due date a business typically pays its bills. A company with a high DBT is essentially using its vendors as a 0% interest loan. You don’t want to be the next “vendor” they decide to pay late.
Legal and Security Checks
A solid report must include:
- Tax Liens and Judgments: Has the government or a court already laid claim to their cash?
- Global Homeland Security Search: This checks against terrorist watchlists and international sanctions.
- Corporate Structure: Is the business actually in “Good Standing” with the Secretary of State in Indiana?
We always remind our owners that Tenant Screening and the CFPB: Making Sure Your Report Isn’t a Horror Story is a real concern. Accuracy matters. Using a “revolutionary” provider like APScreen—which has been a full-service Consumer Reporting Agency since 1980—ensures the data is verified and compliant.
Identifying Financial Red Flags and Mitigating Risk
As property managers in the Granger and Mishawaka areas, we’ve seen it all. Sometimes a business looks great on paper but has “skeletons in the closet” that only a deep-dive screening will find.
Bankruptcy Filings
A recent bankruptcy isn’t always an automatic “no,” but it requires a much higher security deposit or a stronger personal guarantee. You need to know if it was a Chapter 7 (liquidation) or Chapter 11 (reorganization).
Collection Accounts
If a business has open collections from utility companies or previous landlords, that is a massive red flag. It shows a fundamental breakdown in their operational cash flow. We emphasize that property owners should Stop Chasing Checks: Better AR Tracking for Landlords by selecting tenants who have a clean history of electronic payments and vendor relationships.
Inconsistent Payment Trends
We look for “downward trends.” If a business was paying on time two years ago but has steadily moved to 15, then 30, then 45 days past due, they are in a liquidity crunch.
Risk Scoring Models
Some services use proprietary scores like TransUnion’s ResidentScore (for the individual) or Experian’s Intelliscore (for the business). ResidentScore, for instance, is proven to predict rental evictions 15% better than a traditional credit score.
Best Practices for FCRA Compliance and Efficient Leasing
Compliance isn’t just a “nice to have”—it’s a legal requirement. Even in commercial real estate, if you are screening the individual (the principal or the guarantor), you are governed by the Fair Credit Reporting Act (FCRA).
Applicant Authorization
You must have written consent from the applicant before running a credit check. Most commercial tenant screening services provide a digital portal where the applicant can sign and even pay the fee directly.
Adverse Action Notices
If you deny a tenant based on their screening report, you are legally required to provide an “Adverse Action Notice.” This tells them which credit agency provided the data so they can dispute any inaccuracies.
Data Security
In an age of identity theft, you don’t want Social Security numbers or sensitive business tax returns sitting in an unencrypted email folder. Use a secure management platform to store this data.
Integration with Management Software
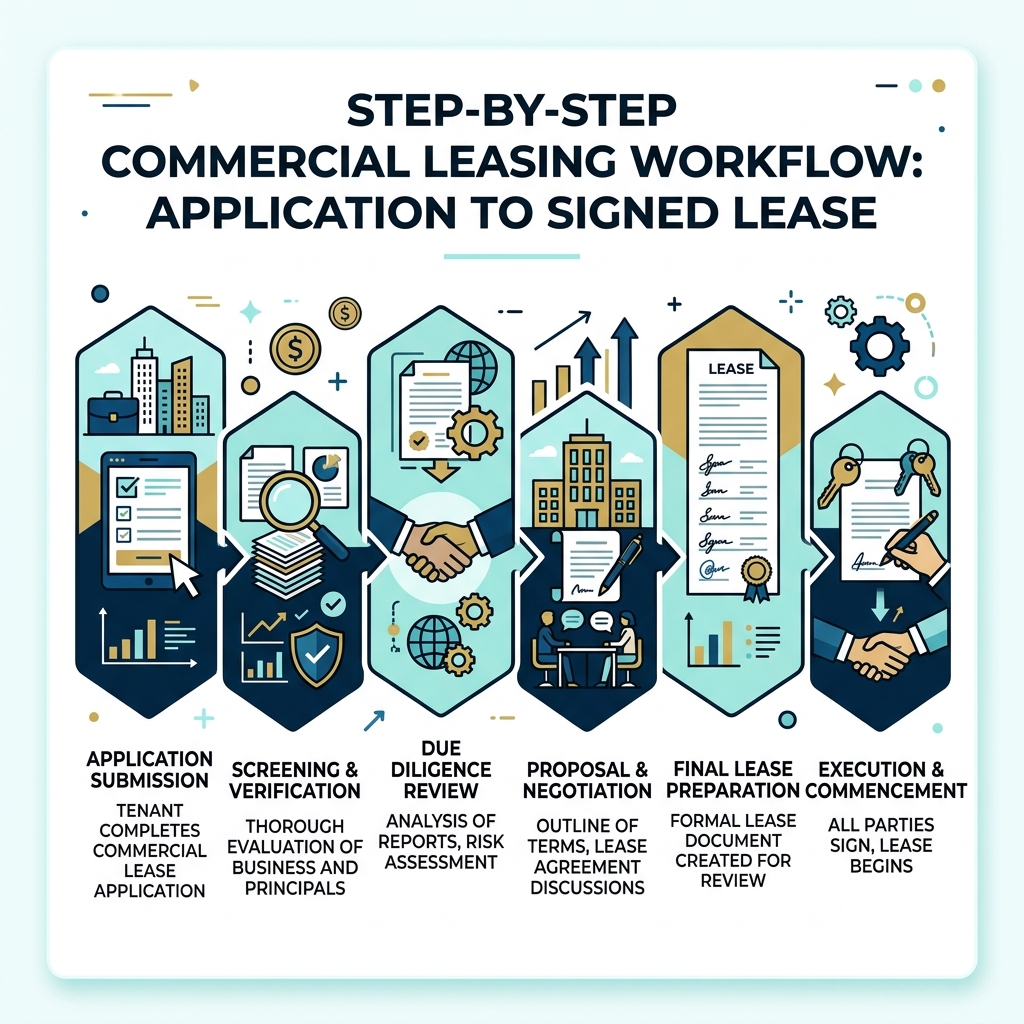
Efficiency is key. Many landlords in the South Bend area use platforms like TenantCloud or AppFolio to integrate screening directly into the leasing workflow. This allows you to:
- Post the listing.
- Collect the application.
- Run the background check.
- Sign the lease. …all in one spot. This can save property managers upwards of 20 hours a month on manual tasks.
Frequently Asked Questions about Commercial Tenant Screening
How much do commercial tenant screening services cost?
Pricing varies based on the depth of the “bundle.” A basic business credit check might start around $25–$40, but a comprehensive commercial tenant screening service like TSCI’s CommercialConnect typically costs around $80 to $85. Some premium reports that include bank asset verification via tools like Plaid can cost more. Many landlords choose the “tenant pays” model, where the applicant covers the cost at the time of application.
What is the turnaround time for commercial tenant screening services?
Most digital reports are available almost instantly or within the same business day if ordered during standard business hours. However, if the screening requires manual “verifications” (like calling a previous landlord or verifying an out-of-state education), it can take 24 to 72 hours. Companies like TenantAlert offer “direct access” for underwritten landlords, which can provide results in minutes.
Should I screen the business or the individual lease signer?
The short answer: Both. Unless you are leasing to a Fortune 500 company, the business entity is only as strong as the people running it. We recommend screening the business for its trade history and the individual principal for their personal financial responsibility. This “dual screening” is the gold standard for mitigating risk, especially for startups or businesses less than two years old.
Conclusion
At the end of the day, your commercial property is only as successful as the tenants inside it. Whether you are managing a small retail strip in Elkhart or a large office complex in South Bend, professional commercial tenant screening services provide the data you need to move from “gut feeling” to “informed decision.”
At Root Management, we take a personalized, scalable approach to Services. We handle the messy details—the FCRA compliance, the UCC filing analysis, and the background checks—so you can focus on growing your portfolio.
Don’t leave your ROI to chance. A few minutes of screening today can save you years of headaches tomorrow. If you’re ready to professionalize your leasing process, we’re here to help.